The most reliable way to learn how to save money on a monthly salary in India is to budget around your actual take-home pay, set aside savings right after payday, track daily UPI and card spending, trim recurring bills, avoid high-interest credit card debt, build a three-to-six-month emergency fund, and match your remaining savings to suitable goals.
Your salary gets credited at the beginning of the month. Within a few days, you pay house rent, electricity bills, groceries, EMIs, mobile recharges, transport costs, and a few subscriptions. Before the next payday arrives, your bank balance looks surprisingly thin, leaving you wondering where most of your money went.
Learning how to save money on a monthly salary in India does not require earning an unusually high income. Most salaried households struggle to save not because they earn too little to start, but because expenses expand to fill whatever sits in the primary bank account.
With a clear monthly budget, steady spending awareness, disciplined transfers on payday, and realistic goal planning, you can build financial stability on almost any regular paycheck. In this guide, you will learn 10 practical saving strategies tailored to Indian salaries, complete with ₹20,000 to ₹1,00,000 illustrative budgets, a copy-ready monthly template, and answers to common salary questions.
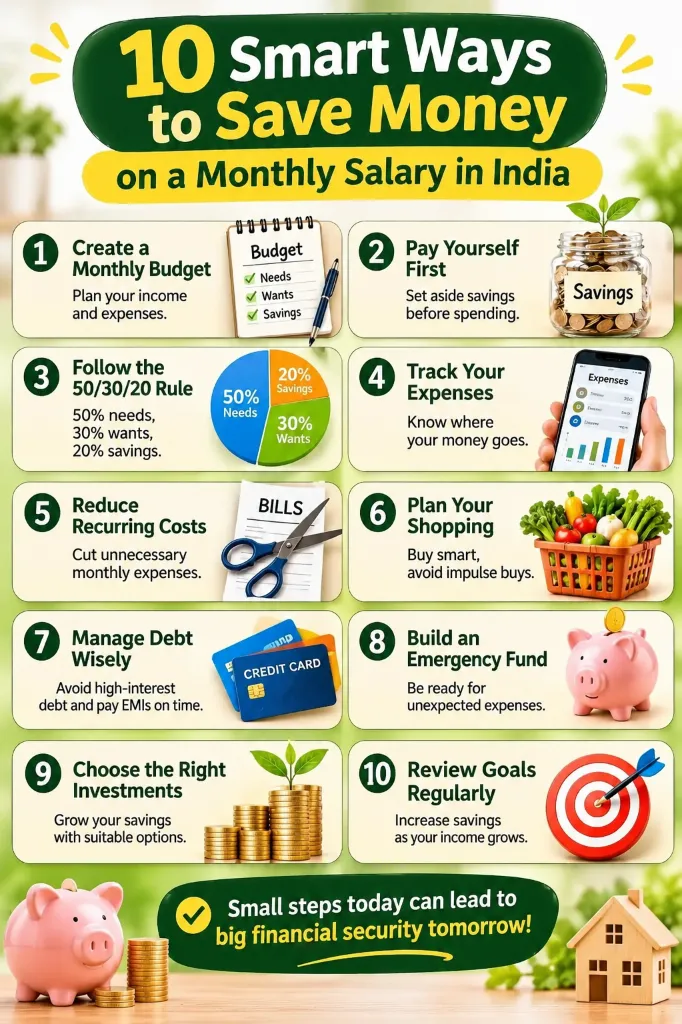
- Quick Answer – 10 Smart Ways to Save Money on a Monthly Salary
- 1. Create a Monthly Budget Before Spending Your Salary
- 2. Pay Yourself First – Save Before You Spend
- 3. Follow the 50/30/20 Budget Rule – Adapt It to Your Salary
- 4. Track Daily Expenses and Control UPI Spending
- 5. Reduce Recurring Household Expenses
- 6. Plan Groceries and Shopping to Avoid Impulse Purchases
- 7. Manage Credit Cards, EMIs and Loans Wisely
- 8. Build an Emergency Fund for Unexpected Expenses
- 9. Choose Suitable Savings and Investment Options
- 10. Review Your Financial Goals and Increase Savings Gradually
- How to Save Money on Different Monthly Salaries in India
- How to Save Money on a Low Salary Without Compromising Basic Needs
- How Much of Your Salary Should You Save Every Month?
- A Simple Monthly Salary Budget Template
- Frequently Asked Questions
- Start Saving Smarter with Every Paycheck
Quick Answer – 10 Smart Ways to Save Money on a Monthly Salary
Before looking at detailed numbers, here is a quick summary of the 10 core habits that help Indian salaried employees keep more of their monthly income.
| No. | Saving strategy | Why it matters |
|---|---|---|
| 1 | Create a monthly budget | Gives control over income and expenses |
| 2 | Pay yourself first | Builds regular saving habits |
| 3 | Follow a flexible 50/30/20 budget | Provides a spending framework |
| 4 | Track daily expenses | Identifies unnecessary spending |
| 5 | Reduce recurring expenses | Frees up monthly cash |
| 6 | Plan groceries and shopping | Prevents impulse purchases |
| 7 | Manage EMIs and credit cards wisely | Reduces interest costs |
| 8 | Build an emergency fund | Provides financial protection |
| 9 | Choose suitable savings and investment options | Supports financial goals |
| 10 | Review and increase savings regularly | Builds long-term discipline |
Even small, consistent savings can build meaningful financial stability over time. The sections below explain how to apply each step to real Indian household bills and salaries.
1. Create a Monthly Budget Before Spending Your Salary
A monthly budget is a written plan for every rupee that enters your bank account before you start paying bills or making UPI transfers. Without a plan, discretionary purchases easily crowd out savings by mid-month.
Always build your budget on your actual monthly take-home salary, not your Cost to Company (CTC) or gross salary. CTC includes employer contributions such as EPF, gratuity, and insurance, while gross salary still has deductions like employee EPF, professional tax, and TDS removed before credit.
Before planning your monthly budget, understand your actual in-hand salary. Use our Salary / CTC Calculator to estimate how much you receive after applicable deductions, or read our step-by-step guide on calculating take-home salary from CTC.
- Fixed expenses: Costs that stay mostly constant each month, such as house rent, loan EMIs, school fees, and insurance premiums.
- Variable expenses: Costs that change based on usage and choices, such as groceries, electricity, water, mobile and internet bills, fuel, transport, medical bills, family support, and entertainment.
- Practical steps: List your net bank credit at the top, subtract fixed bills first, assign realistic caps to variable categories, and set a specific rupee target for savings.
Illustrative Monthly Budget on a ₹50,000 Take-Home Salary
The table below shows an illustrative monthly breakdown for a ₹50,000 net salary. Actual household figures will differ based on city, rent, family size, and existing loans, so replace these numbers with your own bills.
| Expense category | Illustrative monthly amount |
|---|---|
| House rent | ₹12,000 |
| Groceries | ₹6,000 |
| Utilities and mobile | ₹2,000 |
| Transport | ₹3,000 |
| EMIs | ₹5,000 |
| Insurance and medical | ₹2,000 |
| Personal and entertainment | ₹4,000 |
| Savings and financial goals | ₹12,000 |
| Miscellaneous | ₹4,000 |
| Total | ₹50,000 |
- Common mistake to avoid: Budgeting with CTC instead of net bank credit, or leaving out irregular costs like annual insurance premiums and festival travel.
- Actionable takeaway: Write down your exact take-home pay and fixed bills tonight before your next salary arrives.
2. Pay Yourself First – Save Before You Spend
Most people follow the formula Income – Expenses = Savings, hoping something remains on the 28th of the month. In practice, unplanned outings, online sales, and convenience orders usually consume whatever is left in the account.
Flipping that formula to Income – Savings = Available Spending Money changes how you manage cash. As soon as your salary is credited, move your planned savings amount into a separate bank account, recurring deposit, or goal-based investment so you naturally adjust daily spending to the remaining balance.
- Practical steps: Open a dedicated zero-balance or separate savings account without a linked UPI app, or set up an automatic bank transfer dated one or two days after payday.
- Start small if needed: If ₹10,000 feels tight right now, begin with ₹2,000 or ₹3,000 and raise the transfer every few months as bills stabilize.
- Financial illustration: Saving ₹3,000 each month adds up to ₹36,000 in one year (₹3,000 × 12) before counting any interest earned, creating a useful cushion for emergencies or annual expenses.
- Common mistake to avoid: Keeping emergency or goal savings in the same debit-card and UPI account used for daily coffee, cabs, and groceries.
- Actionable takeaway: Schedule an automatic standing instruction for the 2nd or 3rd of every month so saving happens without relying on willpower.
3. Follow the 50/30/20 Budget Rule – Adapt It to Your Salary
The 50/30/20 framework divides monthly take-home pay into three clear buckets: 50% for needs (rent, groceries, utilities, basic transport, minimum loan payments, insurance), 30% for wants (dining out, OTT plans, weekend travel, gadgets), and 20% for savings and extra debt repayment.
| Category | Allocation | Amount (Illustrative ₹50,000 Salary) |
|---|---|---|
| Needs (rent, groceries, bills, basic transport, insurance) | 50% | ₹25,000 |
| Wants (dining out, shopping, entertainment, subscriptions) | 30% | ₹15,000 |
| Savings and extra debt repayment | 20% | ₹10,000 |
| Total | 100% | ₹50,000 |
Treat 50/30/20 as a starting reference rather than a strict rule. High rent in cities like Mumbai, Bengaluru, or Gurugram, supporting parents, school fees, medical costs, or existing EMIs can easily push necessary expenses past 50% of take-home pay.
- Adapt the split: If basic needs take 60% or 65% of your salary, try a 60/20/20 or 65/20/15 split by trimming discretionary wants first rather than giving up on saving altogether.
- Handling EMIs: Count compulsory monthly EMIs under needs so you do not miss due dates, and count extra principal prepayments toward the 20% savings and debt-reduction bucket.
- Common mistake to avoid: Labelling lifestyle upgrades, like frequent food delivery or impulse electronics, as needs just to make the numbers fit.
- Actionable takeaway: Categorize last month's bank statement into Needs, Wants, and Savings to see your real current ratio.
4. Track Daily Expenses and Control UPI Spending
Instant digital payments make life convenient, yet scanning a QR code for ₹80 chai and snacks or ordering ₹250 lunch via an app rarely feels like spending real money. UPI itself does not cause overspending, but friction-free checkout reduces your natural pause before buying.
Small, repeated leaks quietly drain monthly budgets. For example, spending just ₹100 unnecessarily every day equals ₹3,000 per month (₹100 × 30) or ₹36,000 a year, money that could fund a recurring deposit or clear a small loan faster.
- Practical ways to track: Review your UPI transaction history and bank statement every Sunday evening, maintain a simple Google Sheet or spreadsheet, use a basic expense-tracking app, or jot down daily cash and UPI outflows in a pocket notebook.
- Set a weekly discretionary cap: Keep a fixed weekly allowance (for example, ₹1,000 per week for snacks, coffee, and cabs) in a secondary UPI-linked account so overspending shows up immediately.
- Common mistake to avoid: Waiting until the end of the quarter to check card and UPI statements, when you can no longer recall what half the small charges were for.
- Actionable takeaway: Spend 10 minutes every Sunday reviewing the past seven days of UPI and card alerts, and tag the top three avoidable expenses.
5. Reduce Recurring Household Expenses
Cutting a single ₹500 impulse purchase saves money once, whereas lowering a recurring monthly bill saves money twelve times a year with almost no ongoing effort. Auditing fixed and semi-fixed bills twice a year frees up steady cash without lowering your quality of life.
Look closely at electricity usage, broadband and mobile data packs, overlapping OTT subscriptions, unused gym memberships, bank account maintenance fees, and daily commute choices. However, never cancel or under-insure genuine health or term life insurance just to save a small monthly amount, because one medical bill can wipe out years of savings.
| Recurring expense | Practical adjustment | Illustrative monthly saving |
|---|---|---|
| OTT & app subscriptions | Keep 1 active platform at a time; cancel unused auto-renewals | ₹400 – ₹800 |
| Mobile & broadband plans | Switch from oversized data packs to plans matching actual usage | ₹200 – ₹400 |
| Electricity bill | Use 24–26°C AC settings, LED bulbs, and switch off idle appliances | ₹300 – ₹700 |
| Daily commute | Use metro, bus, or carpool twice a week instead of solo cabs | ₹800 – ₹1,500 |
| Illustrative combined saving | Redirected directly to savings on payday | ₹1,700 – ₹3,400 |
*All savings figures above are illustrative examples and depend on your household usage and city tariffs.
- Common mistake to avoid: Letting free trials convert into paid annual renewals, or paying avoidable ATM, SMS, and minimum-balance penalties.
- Actionable takeaway: Open your bank mandate and app-store subscription list today and cancel any service you have not used in the last 30 days.
6. Plan Groceries and Shopping to Avoid Impulse Purchases
Groceries and household supplies take up a major share of Indian family budgets, especially when frequent quick-commerce orders add delivery fees and unplanned snacks. Planning meals for the week and shopping from a written list keeps food waste and impulse spending low.
Compare unit prices (cost per kilogram or per litre) on staples like atta, rice, pulses (dal), cooking oil, milk, and household cleaners. Avoid buying large bulk packs of perishable vegetables or snacks purely for a discount if half of them spoil before use, because wasted food is wasted money.
- Practical steps: Check your kitchen pantry before ordering, batch staple purchases once or twice a month, eat before visiting a supermarket, and apply a 48-hour cooling-off rule before checking out non-urgent online shopping carts.
- Financial illustration: Trimming two unplanned ₹450 quick-commerce snack orders per week saves ₹3,600 a month (₹450 × 8) without cutting a single regular meal.
- Common mistake to avoid: Buying items you never planned to purchase simply to reach a "free delivery" threshold or "buy two, get one" promo.
- Actionable takeaway: Write a fixed weekly grocery list on Saturday and stick to it when ordering or visiting the market.
7. Manage Credit Cards, EMIs and Loans Wisely
High-interest debt works directly against your ability to save. As the Reserve Bank of India (RBI) financial education resources highlight, paying only the "minimum amount due" on a credit card keeps your account active while steep interest charges accumulate on the unpaid balance.
Watch out for overlapping EMIs across personal loans, vehicle loans, consumer durables, and "no-cost EMI" offers. Even when a merchant advertises a no-cost EMI, you may still face processing fees, GST on the interest component, or lose an upfront cash discount that was available on full payment.
Planning a loan? Use our EMI Calculator to estimate your monthly repayment and understand its impact on your budget. You can also check our Credit Card EMI Calculator, read how loan EMI and prepayment work, or check your borrowing load with our Debt-to-Income Ratio guide.
Illustrative Impact of Multiple EMIs on Disposable Income (₹50,000 Salary)
| Scenario (₹50,000 take-home) | Monthly EMIs | Core bills | Remaining for wants & savings |
|---|---|---|---|
| Low debt (no consumer EMIs) | ₹0 | ₹25,000 | ₹25,000 |
| Moderate debt (1 vehicle/education EMI) | ₹7,000 | ₹25,000 | ₹18,000 |
| Heavy debt (phone + personal + card EMIs) | ₹16,000 | ₹25,000 | ₹9,000 |
- Practical steps: Always pay your full credit card statement balance before the due date, prioritise paying off the highest-interest debt first, and check prepayment or foreclosure clauses before signing any loan agreement.
- Common mistake to avoid: Converting routine lifestyle purchases into 6-month or 12-month EMIs just because the monthly instalment looks small.
- Actionable takeaway: List every active loan and credit card balance with its interest rate and due date, and avoid adding any new EMI until existing short-term debt is cleared.
8. Build an Emergency Fund for Unexpected Expenses
An emergency fund is money set aside strictly for genuine surprises such as job loss, a sudden hospitalisation, urgent home or vehicle repairs, or an unexpected family crisis. Without this buffer, even a disciplined saver is forced to break long-term investments or swipe a credit card at high interest.
A widely used planning guideline is to hold roughly three to six months of core living expenses (rent, groceries, utilities, EMIs, and insurance) in an easily accessible place. Treat this as a flexible target rather than a rigid rule: single earners or people in unstable industries may aim higher, while dual-income households might start with three months.
- Financial illustration: If your household's core monthly expenses total ₹25,000, a three-month emergency fund is ₹75,000 (₹25,000 × 3) and a six-month fund is ₹1,50,000 (₹25,000 × 6).
- Where to keep it: Keep emergency reserves in liquid, low-risk options such as a separate high-liquidity savings account, a sweep-in FD, or a short-term bank deposit with clear withdrawal rules, never in volatile equity funds where markets could drop right when you need the cash.
- Start step by step: Begin with a starter milestone of ₹15,000 or one month of expenses, build steadily, and adjust the target whenever your rent or family responsibilities grow.
- Common mistake to avoid: Dipping into the emergency fund for festival shopping, gadget upgrades, or planned vacations.
- Actionable takeaway: Calculate three months of your bare-minimum household bills today and open a separate bucket dedicated solely to that safety net.
9. Choose Suitable Savings and Investment Options
Saving and investing serve different purposes. Saving means setting money aside in safe, accessible accounts for short-term needs and emergencies, while investing means putting money into assets that can grow over longer horizons while carrying varying levels of risk.
No single product fits every goal. Savings accounts, Fixed Deposits (FDs), Recurring Deposits (RDs), Public Provident Fund (PPF), Employee Provident Fund (EPF), National Pension System (NPS), and Mutual Fund Systematic Investment Plans (SIPs) differ sharply in liquidity, lock-in periods, tax rules, and risk.
| Financial option | Main purpose | Key consideration |
|---|---|---|
| Savings account | Daily access and short-term reserves | High liquidity and applicable bank interest |
| Recurring Deposit (RD) | Disciplined monthly saving | Fixed monthly deposit commitment and tenure |
| Fixed Deposit (FD) | Planned savings for a fixed period | Applicable interest rate, tenure, and premature withdrawal rules |
| Public Provident Fund (PPF) | Long-term savings | 15-year lock-in structure and applicable government rules |
| EPF | Retirement savings for eligible salaried employees | Employer-employee contributions and specific withdrawal rules |
| NPS | Long-term retirement planning | Market exposure, tier rules, and withdrawal conditions |
| Mutual Fund SIP | Goal-based long-term investing | Market risk and suitable investment horizon |
Keep two core rules in mind when comparing options. First, a Systematic Investment Plan (SIP) is an automated method of investing regularly into a mutual fund, not a guaranteed-return product; mutual fund investments are subject to market risks and returns fluctuate. Second, never put money you need within the next one to two years into equity-linked instruments.
Verify current interest rates, lock-in clauses, and tax treatment under your chosen regime on official portals such as the National Savings Institute (NSI), EPFO, PFRDA, AMFI, or the Income Tax Department before committing funds.
Want to understand how regular monthly investments may grow over time? Explore our SIP Calculator, or use our Compound Interest Calculator to see how compounding affects long-term savings. You can also explore our RD Calculator, FD Calculator, PPF Calculator, Income Tax Calculator, and Retirement Planner, or read SIP vs Lumpsum Investing and Compound vs Simple Interest.
- Common mistake to avoid: Locking away emergency cash in long-tenure products, or chasing short-term market returns with next year's rent or wedding fund.
- Actionable takeaway: Match each rupee you save to a timeline: liquid accounts for under 1 year, deposits for 1–3 years, and goal-aligned long-term instruments for 5+ years.
10. Review Your Financial Goals and Increase Savings Gradually
Saving feels much easier when your money has a clear job. Dividing goals into short-term (1–2 years, such as an emergency fund, laptop, or family trip), medium-term (3–5 years, such as higher education, vehicle purchase, or home down payment), and long-term (7+ years, such as children's education or retirement) gives purpose to every monthly transfer.
As your salary grows, guard against lifestyle inflation, the habit of upgrading your rent, phone, car, and dining budget every time you get an appraisal. Redirecting even half of your annual increment or bonus straight into savings lets your lifestyle improve comfortably while your financial security accelerates.
Explore our Retirement Planner to estimate your future financial requirements, and read how inflation affects long-term goals in our Inflation Calculator guide and Retirement Corpus guide.
- Financial illustration: If your monthly take-home pay rises by ₹5,000 after an appraisal and you move ₹2,500 into savings while keeping ₹2,500 for lifestyle upgrades, you add ₹30,000 more per year to your goals without feeling deprived.
- Common mistake to avoid: Spending 100% of annual bonuses on impulse upgrades before checking your emergency fund or high-interest debt.
- Actionable takeaway: Set a calendar reminder at the end of every month for a 15-minute budget check, and do a full goal review every April after your increment cycle.
How to Save Money on Different Monthly Salaries in India
How much you can save depends heavily on whether you live with family or pay metro rent, whether you support dependents, and whether you carry existing EMIs. A person earning ₹30,000 in a tier-1 city paying ₹10,000 rent has a very different cash flow from someone earning ₹30,000 while living at home.
The table below provides illustrative examples across five common Indian take-home salary levels. These are starting illustrations, not prescribed rules.
| Monthly take-home salary (Illustrative) | Core living expenses | Discretionary spending | Illustrative savings | Practical focus |
|---|---|---|---|---|
| ₹20,000 | ₹15,000 | ₹3,000 | ₹2,000 (10%) | Build starter emergency buffer; avoid all card/consumer debt |
| ₹30,000 | ₹20,000 | ₹5,500 | ₹4,500 (15%) | Separate emergency fund + small monthly RD or goal transfer |
| ₹50,000 | ₹28,000 | ₹12,000 | ₹10,000 (20%) | Complete 3–6 month safety net + start goal-based investing |
| ₹75,000 | ₹38,000 | ₹18,000 | ₹19,000 (~25%) | Diversify across emergency liquid funds, retirement, and medium-term goals |
| ₹1,00,000 | ₹45,000 | ₹25,000 | ₹30,000 (30%) | Step up long-term wealth building, tax planning, and prepay costly loans |
How to Save Money on a Low Salary Without Compromising Basic Needs
If your take-home pay is ₹15,000 to ₹25,000 and you have rent or family expenses, saving 20% immediately may be unrealistic. Struggling to save on a tight income is often a result of rising living costs and family duties, not poor personal discipline.
- Protect basic needs first: Never compromise nutritious food, necessary medicines, or core shelter just to hit an arbitrary savings percentage.
- Start with whatever fits: Even saving ₹500 or ₹1,000 a month builds the habit and creates ₹6,000 to ₹12,000 in a year as an emergency cushion.
- Avoid high-cost borrowing: Stay away from payday apps, credit card revolving balances, and unnecessary consumer EMIs that eat into future paychecks.
- Control small leaks: Cook simple home meals, carry lunch to work when possible, use public transport, and track every UPI payment.
- Grow earning capacity: Alongside careful budgeting, invest time in job skills, certifications, or better-paying roles to widen the gap between income and expenses over time.
How Much of Your Salary Should You Save Every Month?
There is no single savings percentage that works for every Indian employee. A 10% target can serve as a realistic starting point if you are just beginning your career or repaying education loans, while 20% or more is a common medium-term guideline once basic stability is in place.
Separate your emergency savings from long-term investments, and remember that clearing high-interest debt (such as a 36%+ APR credit card balance or expensive personal loan) often delivers a better financial outcome than putting extra cash into low-yield accounts while debt compounds against you.
- ₹30,000 salary example: Saving 10% sets aside ₹3,000/month (₹36,000/year); reaching 15% sets aside ₹4,500/month (₹54,000/year).
- ₹50,000 salary example: Saving 15% sets aside ₹7,500/month (₹90,000/year); reaching 20% sets aside ₹10,000/month (₹1,20,000/year).
A Simple Monthly Salary Budget Template
Copy the structure below into Excel, Google Sheets, or a notebook at the start of each month. Keep the core formula in mind: Savings = Total Income – Total Expenses (and aim to transfer your planned savings first).
| Budget section | Line items to include | Planned (₹) | Actual (₹) |
|---|---|---|---|
| 1. Monthly Income | Take-home salary + any additional income = Total Income | ₹ ______ | ₹ ______ |
| 2. Fixed Expenses | Rent, EMIs, insurance premiums, school fees, fixed utilities | ₹ ______ | ₹ ______ |
| 3. Variable Expenses | Groceries, transport/fuel, food delivery, shopping, entertainment, medical | ₹ ______ | ₹ ______ |
| 4. Savings & Goals | Emergency fund, short-term goals, long-term investments, retirement | ₹ ______ | ₹ ______ |
| 5. Month-End Review | Total income, total expenses, total savings, planned vs actual gap | ₹ ______ | ₹ ______ |
Frequently Asked Questions About Saving Money on a Monthly Salary
1. How can I save money from my monthly salary in India?
You can save money from your monthly salary by budgeting around your net take-home pay, transferring a fixed saving amount right after payday, tracking daily UPI spending, trimming unused subscriptions, and avoiding unnecessary EMIs. Starting with even a small, automatic transfer builds steady financial discipline over the year.
2. How much of my salary should I save every month?
There is no universal saving percentage for everyone, because rent, family responsibilities, and debt vary widely. Many beginners start with 10% of take-home pay and gradually work toward 20% or more as income grows. Always choose a realistic number you can sustain every month without skipping basic bills.
3. How can I save money on a ₹30,000 salary?
On a ₹30,000 take-home salary, focus on keeping fixed rent and transport manageable, cooking meals at home, avoiding credit card or gadget EMIs, and setting aside ₹2,000 to ₹4,500 on payday. Keep that money in a separate savings account or recurring deposit until you build a starter emergency buffer.
4. How can I manage a ₹50,000 monthly salary?
To manage a ₹50,000 take-home salary, list fixed needs such as rent, groceries, utilities, and EMIs first, cap discretionary dining and shopping, and automate ₹10,000 to ₹12,000 toward savings and financial goals. Reviewing your UPI statement weekly helps prevent small convenience orders from eating into your savings target.
5. What is the 50/30/20 rule for monthly budgeting?
The 50/30/20 rule is a simple budgeting framework that divides take-home pay into 50% for needs, 30% for wants, and 20% for savings and extra debt repayment. In high-rent Indian cities or single-earner households, you can adapt it to 60/20/20 or another split that fits your actual bills.
6. Where should I keep my emergency fund?
Keep your emergency fund in safe, accessible places such as a separate savings account, a sweep-in fixed deposit, or a low-risk deposit with clear withdrawal rules. Avoid putting emergency cash into equity mutual funds or locked long-term schemes, because you need quick access without market-drop losses during an urgent crisis.
7. How can I reduce monthly household expenses?
You can reduce monthly household expenses by planning weekly grocery lists to cut food waste, cancelling unused OTT and app renewals, matching mobile or broadband plans to real usage, using energy-saving habits for electricity, and choosing metro or carpooling over frequent solo cab rides. Never cut necessary health or term insurance.
8. Should I save money before paying discretionary expenses?
Yes, paying yourself first after covering compulsory fixed bills works much better than saving whatever happens to remain at month-end. Once your planned savings move to a separate account right after salary credit, you naturally pace dining out, shopping, and entertainment within the balance left for the month.
9. Is it better to repay debt or start investing?
High-interest debt such as unpaid credit card balances or costly personal loans usually deserves top priority after building a small starter emergency cushion, because steep borrowing interest often outweighs conservative deposit returns. For lower-interest long-term loans like home loans, many people balance regular EMIs alongside steady goal-based saving.
10. How can I increase my savings after a salary hike?
Whenever you receive an annual increment or bonus, decide in advance to direct at least half of the raise straight into your savings or investment transfers before upgrading your lifestyle. Automating the higher transfer in the same month prevents lifestyle inflation from quietly absorbing your extra income.
Start Saving Smarter with Every Paycheck
Learning how to save money on a monthly salary in India comes down to repeatable habits rather than complicated spreadsheets. Start by budgeting on your actual take-home pay, moving savings to a separate account right on payday, tracking daily UPI and card outflows, trimming unused recurring bills, and keeping credit card balances paid in full.
Once you have a three-to-six-month emergency cushion in place, match your remaining monthly savings to clear short-term, medium-term, and long-term goals using suitable deposits, retirement schemes, or goal-aligned investments, and review your progress every month.
Saving money is not only about how much you earn. It is also about how consistently you manage your income and make informed financial decisions. Explore our Salary Calculator, EMI Calculator, SIP Calculator, Compound Interest Calculator, and Retirement Planner to plan your next step.
References and Official Sources
- Securities and Exchange Board of India (SEBI) – Investor Education Portal & Management of Income and Expenses
- Reserve Bank of India (RBI) – Financial Education Initiative
- National Savings Institute (NSI) – Small Savings Schemes (PPF, RD, FD Guidelines)
- Employees' Provident Fund Organisation (EPFO) – Official EPF Rules & Member Services
- Pension Fund Regulatory and Development Authority (PFRDA) – National Pension System (NPS) Information
- Association of Mutual Funds in India (AMFI) – Mutual Fund & Investor Awareness
- Income Tax Department, Government of India – Tax Regimes & Filing Guidelines
- How to Calculate Take Home Salary from CTC in India
- How to Calculate Loan EMI: Formula, Amortization & Prepayment
- SIP vs Lumpsum Investment: Which Strategy Fits Your Goals?
- Compound vs Simple Interest: Formula & Examples
- How to Calculate Your Retirement Corpus
- Explore All SmartCalc Financial Calculators